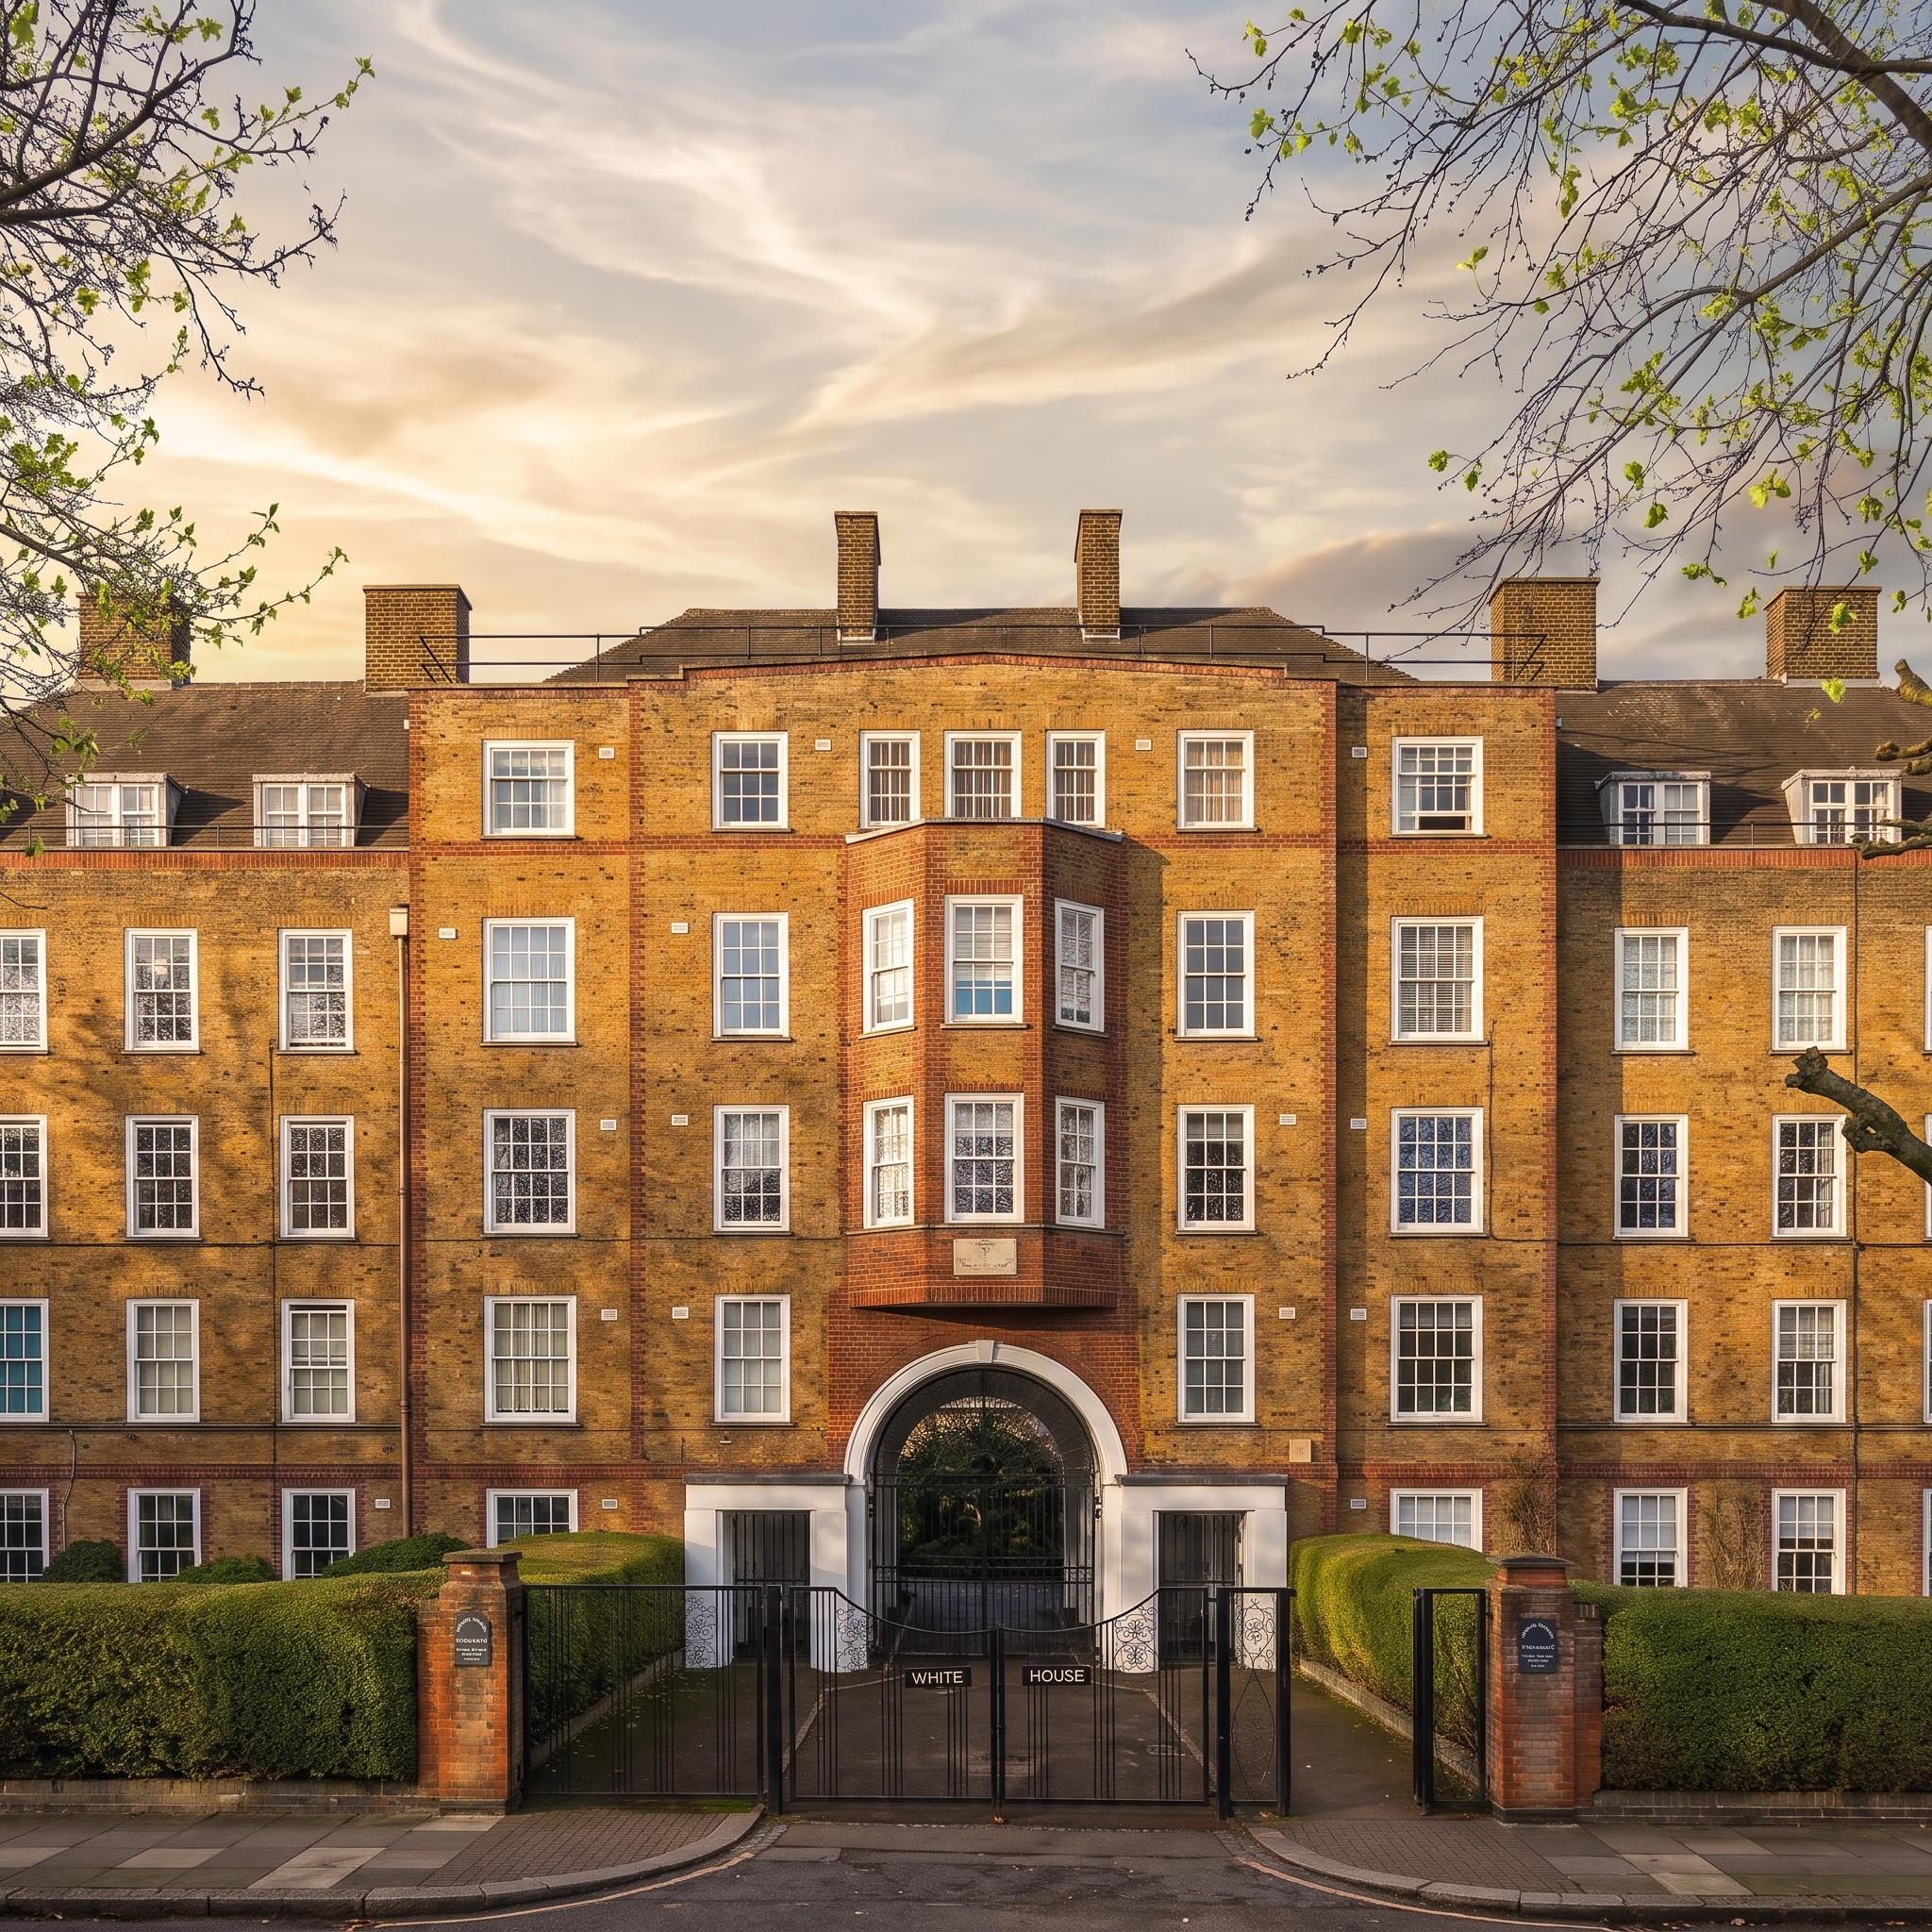
Finding an ex local authority mortgage that works can be harder than finding the property itself. A Battersea first-time buyer had found the perfect flat, an ex-local authority apartment in the block where she was already renting. She knew the building, the neighbours and the area. But what looked like a straightforward first-time buyer purchase became more complicated when the property’s history and structure began restricting the lender pool.
What was the situation?
The client had been renting in a Battersea apartment block and was ready to buy her first home. When a flat in the same building came on the market, it felt like an ideal opportunity. She knew the property worked, the commute was manageable, and she wouldn’t have to uproot her life.
Her parents had introduced her to Oakstead, and after an initial call, we advised her on the implications of buying a leasehold property. She wanted to move quickly, so we reserved a mortgage rate with a high street lender as rates were rising. Then the property search began, and a flat in her own block became available.
What made this ex-local authority flat mortgage difficult?
The property was an ex-local authority apartment. That alone reduces the number of lenders willing to offer a mortgage. Many mainstream lenders either exclude ex-local authority properties outright or apply stricter criteria around lease length, property type and building structure.
This particular flat had three complicating factors:
- Lease length: The lease had 86 years remaining. That was above the threshold that triggers an automatic valuation reduction, but still short enough to concern some lenders. (If you’re weighing up a shorter lease, the official government guidance on extending a lease is a useful starting point.)
- Balcony access: The block had balcony access rather than an internal corridor, which some lenders view as non-standard construction.
- Number of floors: The building had more floors than the lender we’d initially reserved with would accept under their ex-local authority criteria.
We had to pivot quickly. The client wanted to move as soon as possible, and the window to secure the property was narrow.
How did we find the right lender?
We reassessed the lender panel with the property’s characteristics in mind. A mortgage on an ex-local authority flat needs a lender who is comfortable with the construction type, the tenure and the building’s configuration. Not all lenders treat balcony access as standard, and floor count can be a deal-breaker for some.
We approached a lender who have a more flexible criteria for ex-local authority properties and were willing to lend on the building despite its layout. The 86-year lease was acceptable without requiring an immediate extension, which kept upfront costs down. The loan-to-value was mainstream at 78%, so the focus was entirely on property acceptability rather than deposit size.
We structured the application to address the lender’s underwriting requirements around leasehold tenure and building type. We also made sure the valuation reflected the property accurately within the context of ex-local authority housing stock in the area. If you’re a first-time buyer, this kind of upfront property checking can save weeks.
What was the outcome?
The mortgage offer was issued in eight working days. The client secured a two-year fixed rate at 5.15% and could move forward with the purchase of a property she already knew worked for her.
She had certainty. She could stop renting and start preparing for the move into a home she owned, in a building she was already familiar with. The speed mattered, not just because of the market, but because she was ready to take the next step.
Buying an ex-local authority flat? Lender choice is everything
If you’re looking for an ex-local authority flat mortgage, or buying a leasehold flat with a shorter lease, lender choice is everything. The right lender will treat the property as acceptable, not marginal. The wrong one will decline or delay. As a whole-of-market broker, we’ll work out which lenders fit your property before you waste time on an application that was never going to proceed.