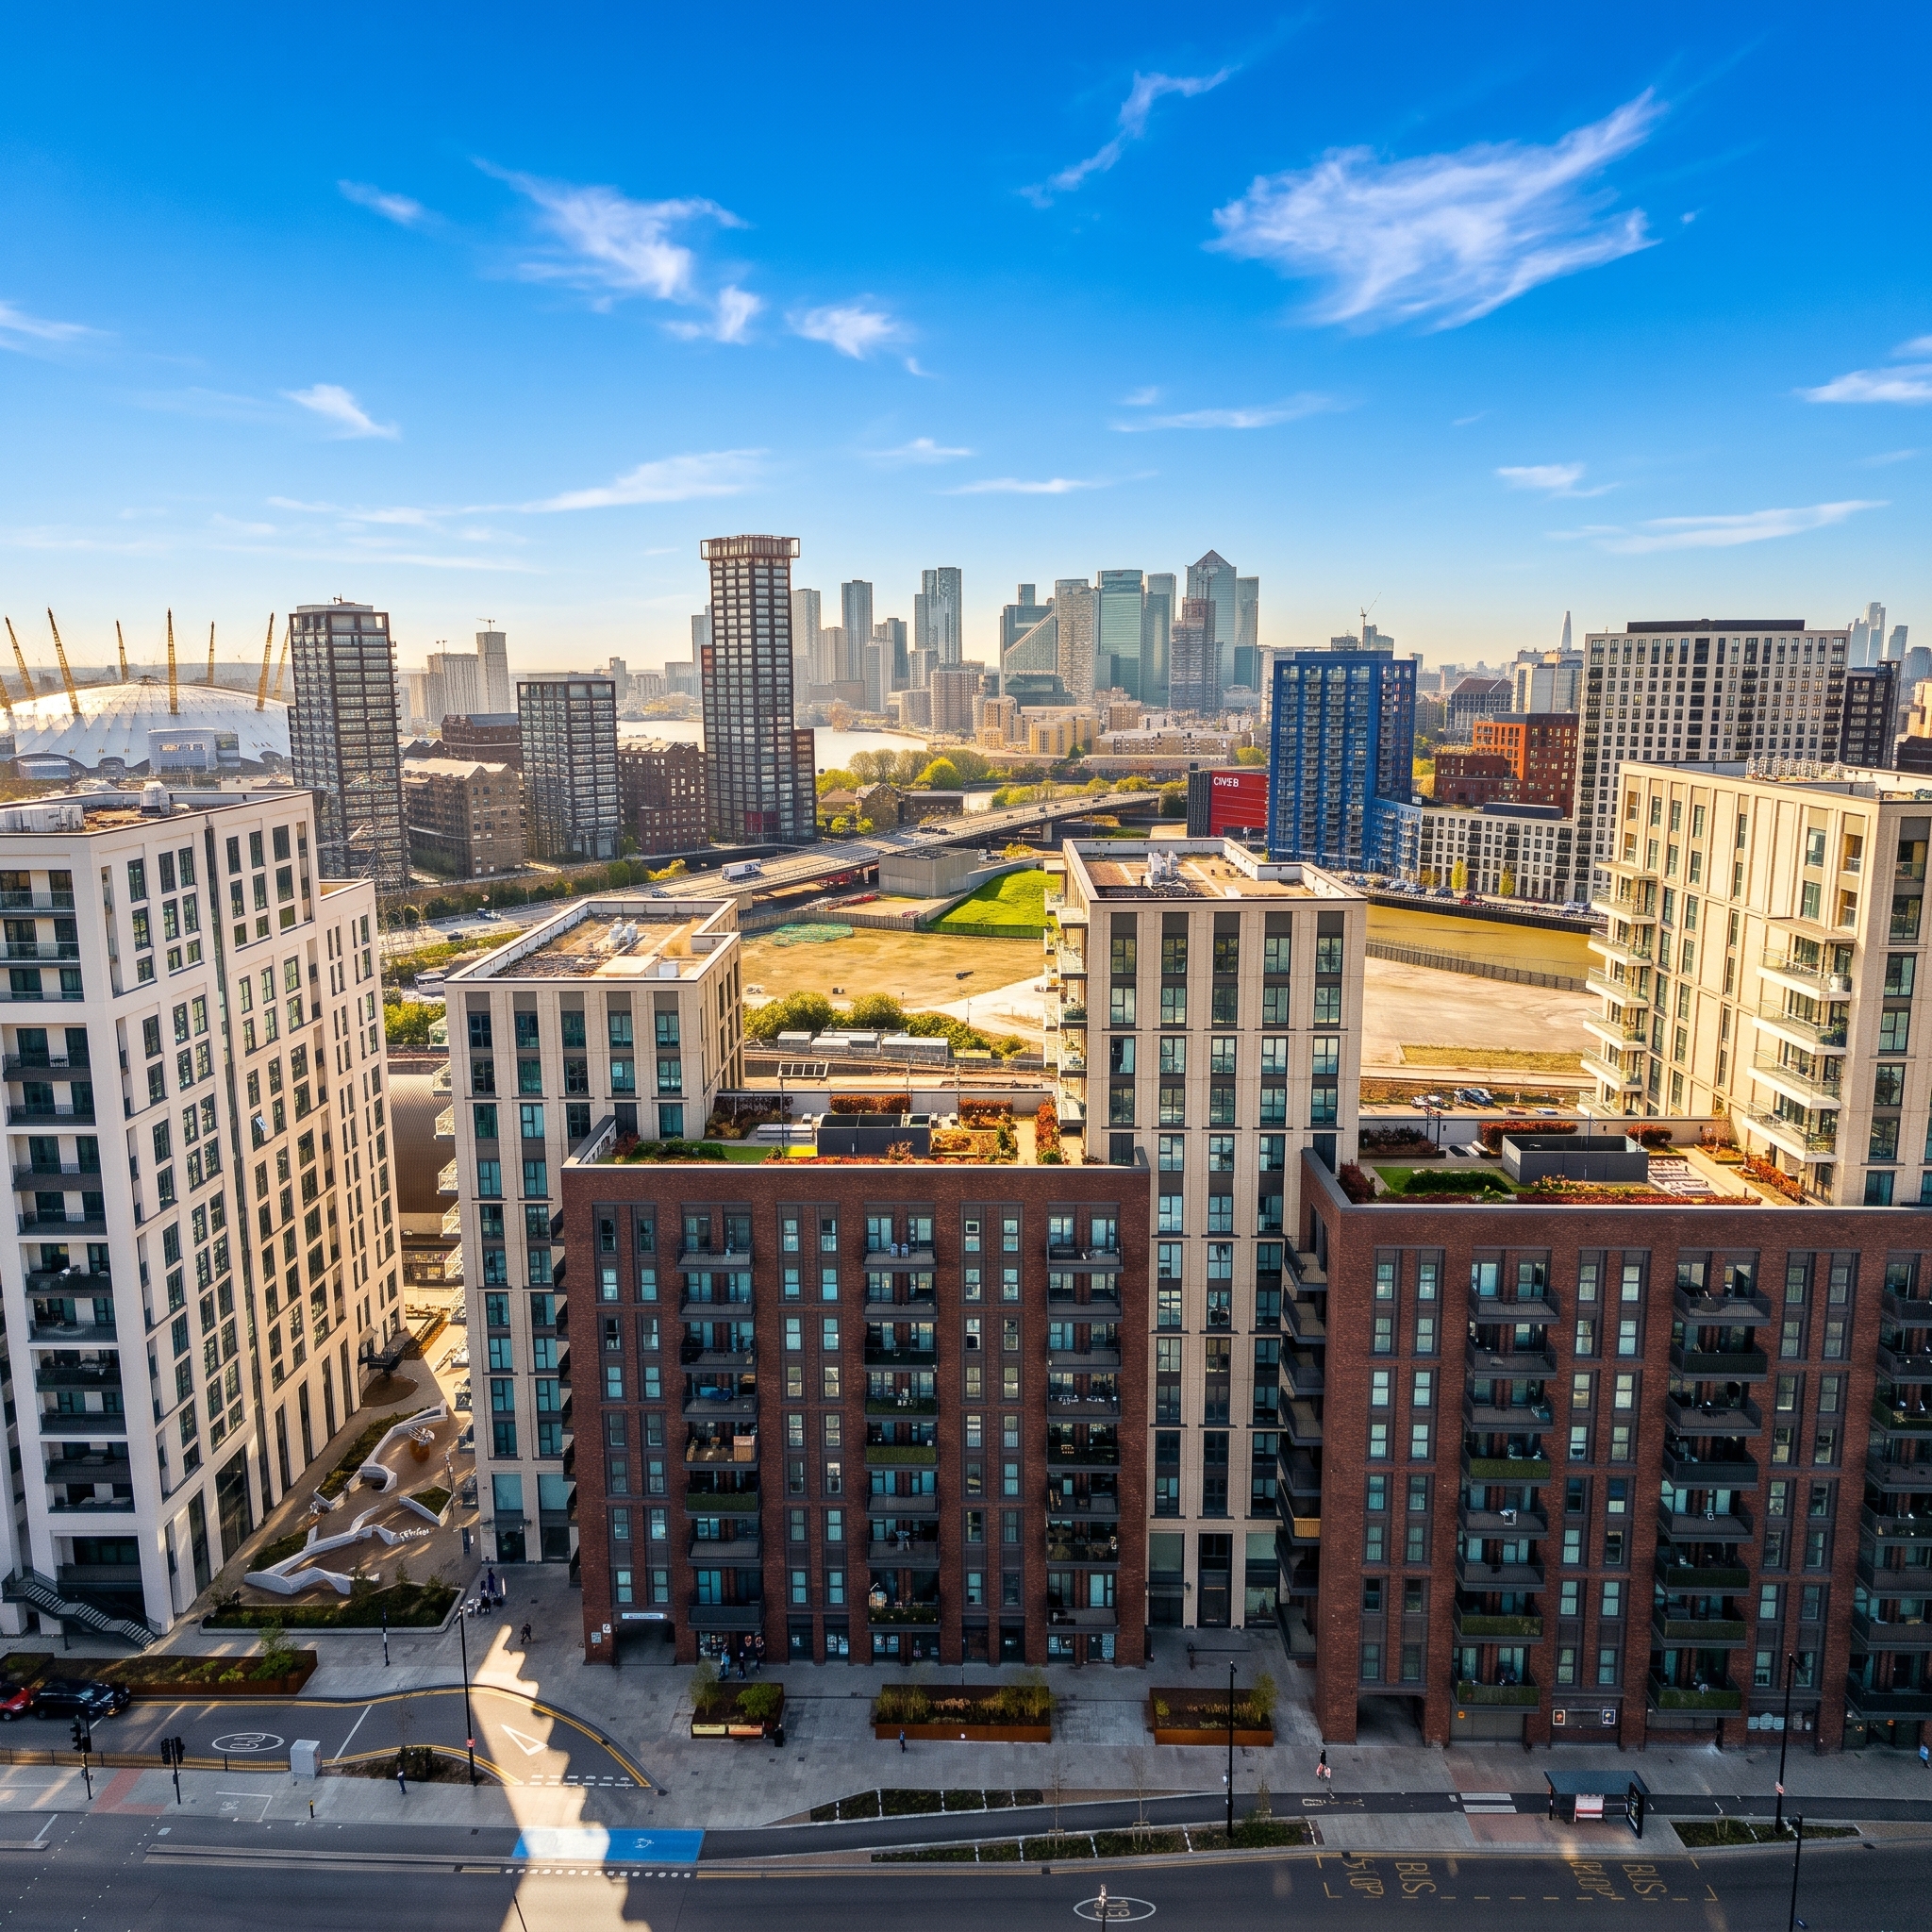
A Canning Town homeowner had purchased his property at the end of 2024. Now, with a new job and a higher salary, he wanted to remortgage to release funds for his first rental investment — but his fixed rate was ending in 75 days. The challenge was clear: could a property bought so recently in a difficult sales market support the valuation needed to release £39,000 in equity?
Why did he need to remortgage to release funds?
The client owned a property in Canning Town, which he bought for £310,000 in late 2024. He had recently started a new role on a higher salary and wanted to use his improved financial position to release equity and fund his first buy-to-let purchase.
His fixed rate was due to expire in just over two months. Without a remortgage in place, he would revert to his lender’s standard variable rate, which would be an expensive outcome just as he needed to fund a second purchase.
What was the challenge?
He had owned the property for less than two years. In a flat or falling sales market, lenders rarely value a property above its recent purchase price unless there is clear evidence of improvement or comparable sales to support it.
He needed to borrow £297,500 against a property bought for £310,000, a loan-to-value of 96%. That would not work. To release the full £39,000, the property had to be valued above its purchase price, and the loan-to-value had to fall within the limits of a remortgage product.
The timeframe added pressure. With 75 days until his fixed rate ended, there was little room for valuation delays or lender indecision.
What did we do?
We reviewed products across the whole market and focused on lenders with a track record of supporting recent purchases and competitive pricing on shorter-term tracker products. The client’s higher salary strengthened his affordability, which opened up options that might otherwise have been unavailable.
We instructed a valuation immediately after submitting the application. It came back above the purchase price, not as high as we had hoped, but enough to bring the loan-to-value down to 90%. We kept the borrowing at the level he needed and moved to a lender offering a two-year tracker at that tier.
This did two things. It kept his monthly cost low while he funds a second property purchase, and it let us release the full £39,000 without compromising the deal.
We requested documentation straight away, and an agreement in principle followed the next day. Once the full application was submitted, the formal mortgage offer was issued in six working days.
What was the outcome?
The client secured £39,000 in released equity, enough to fund the deposit and costs on his first buy-to-let property. The remortgage completed before his fixed rate expired, avoiding any reversion to a higher standard variable rate.
By acting quickly and adjusting the loan-to-value mid-process, we turned a valuation shortfall into a completed case. The client now has the capital he needs to build his property portfolio, with a low-cost tracker in place while he focuses on his next acquisition.
If you are looking to release equity from a recently purchased property or need a remortgage structured around a tight deadline, Oakstead Finance can help.